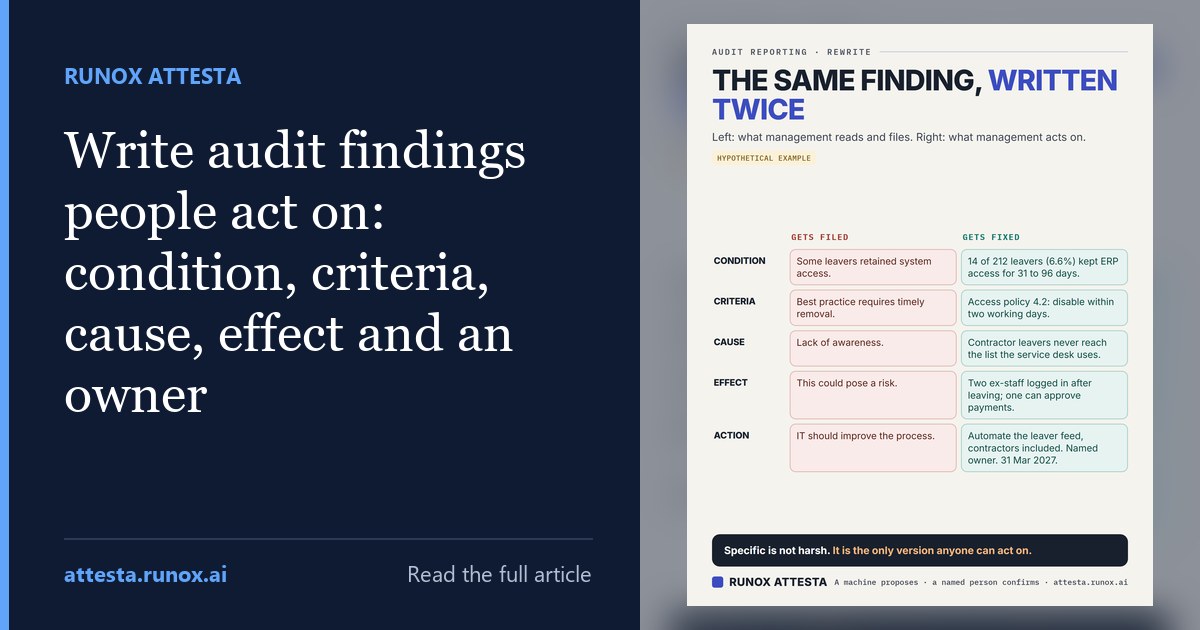
Write audit findings people act on: condition, criteria, cause, effect and an owner
A finding with no named owner and no date is a wish. The five parts of a finding, how the IIA's 2024 Standards frame them, and a rewrite.
Expert insights on tax, legal, HR, accounting, compliance, and business technology to help your team thrive in the digital age.

A finding with no named owner and no date is a wish. The five parts of a finding, how the IIA's 2024 Standards frame them, and a rewrite.
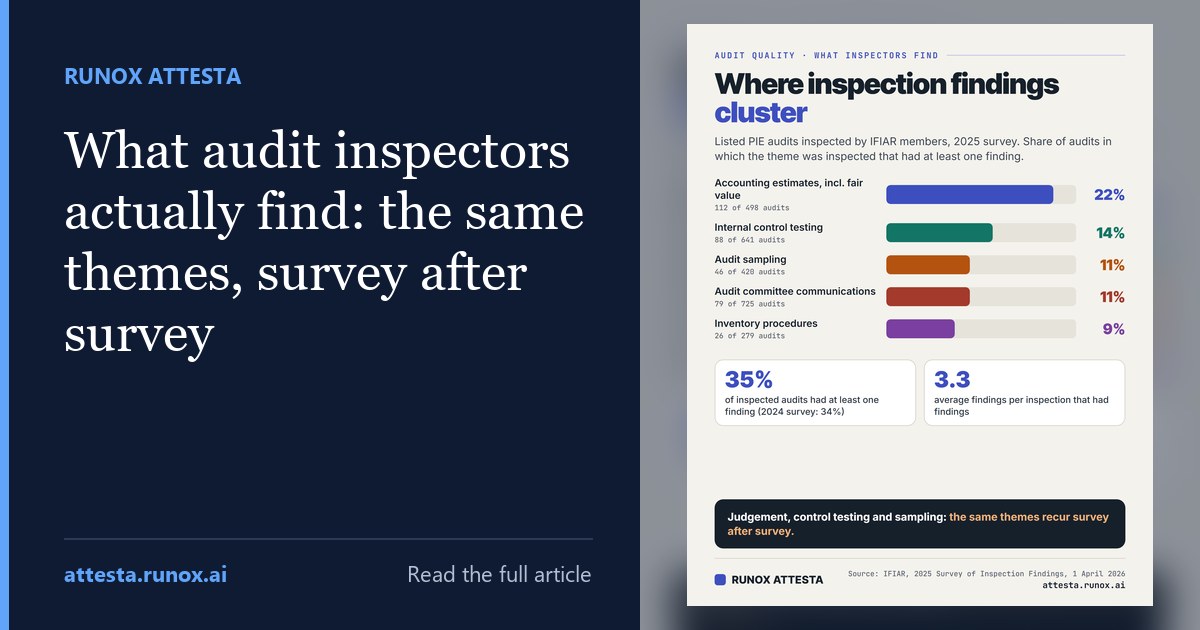
Audit & AssuranceRegulators publish where audit files fail. Estimates, control testing, sampling and untested reports keep returning. Read your file the way they do.
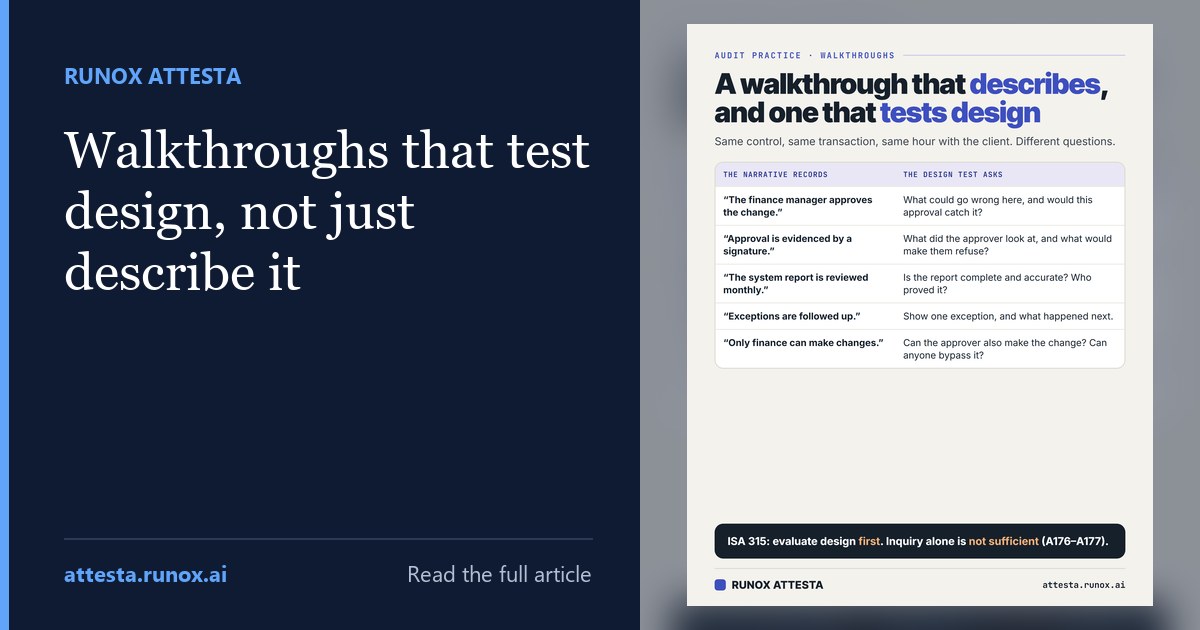
Audit & AssuranceMost walkthroughs record how a process works. ISA 315 asks whether each control could catch the error. Five questions turn one into a design test.
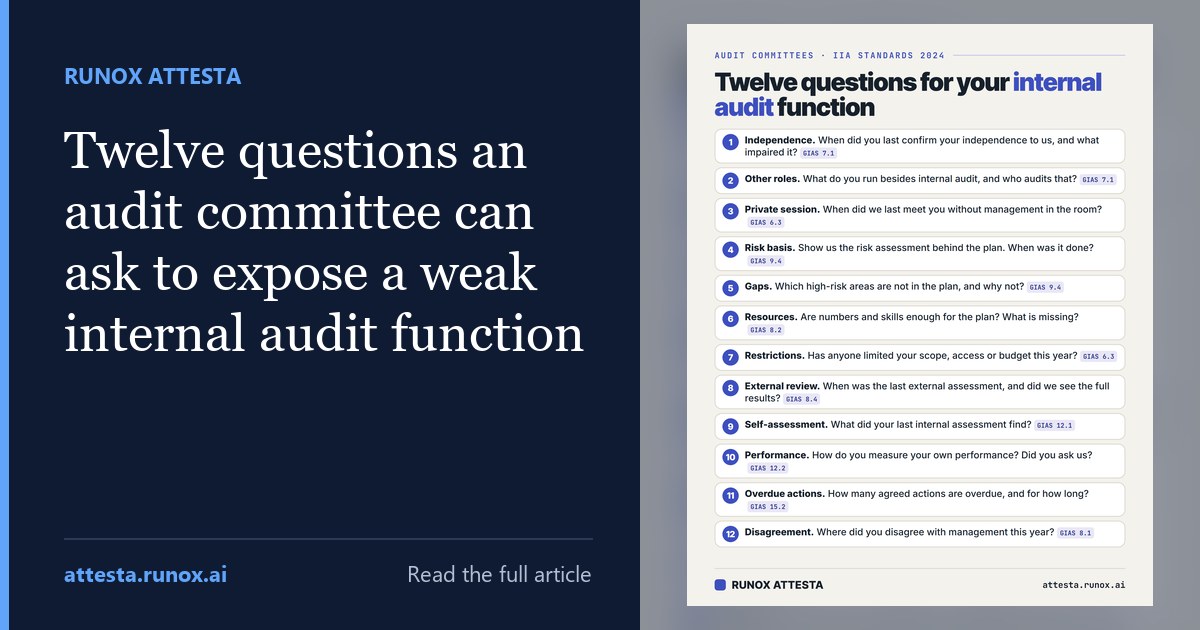
Audit & AssuranceThe IIA's 2024 Standards put duties on the board as well as the auditors. Twelve questions, each tied to a Standard, and what a weak answer sounds like.
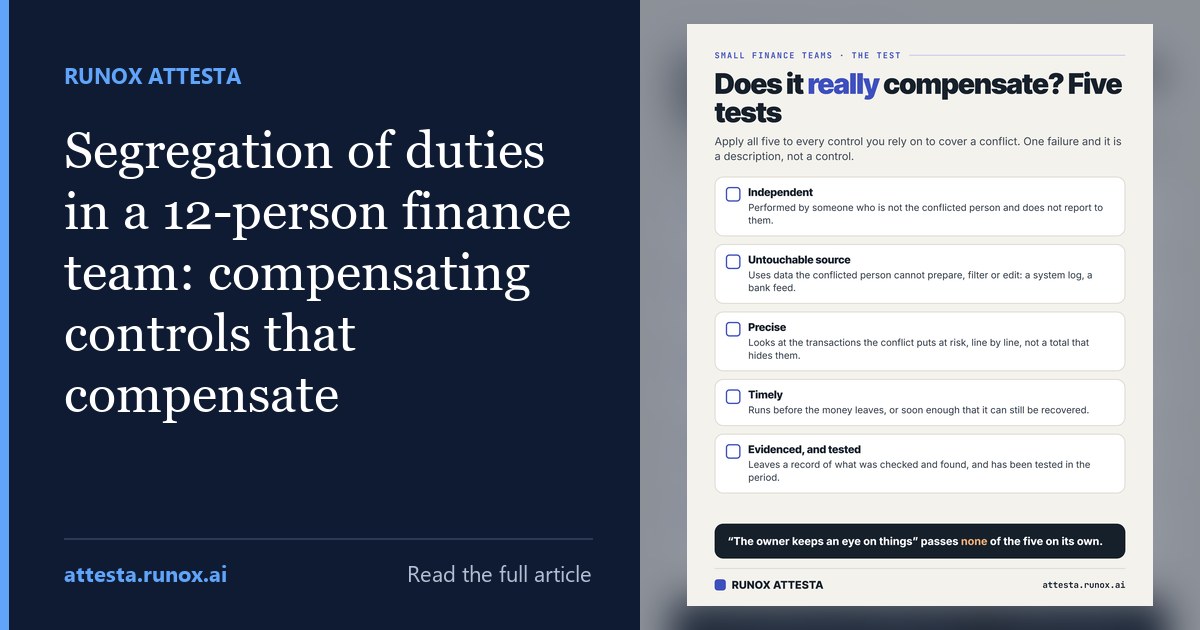
Audit & AssuranceSmall teams cannot split every duty. Most compensating controls are descriptions, not controls. Five tests tell you which ones actually cover the gap.
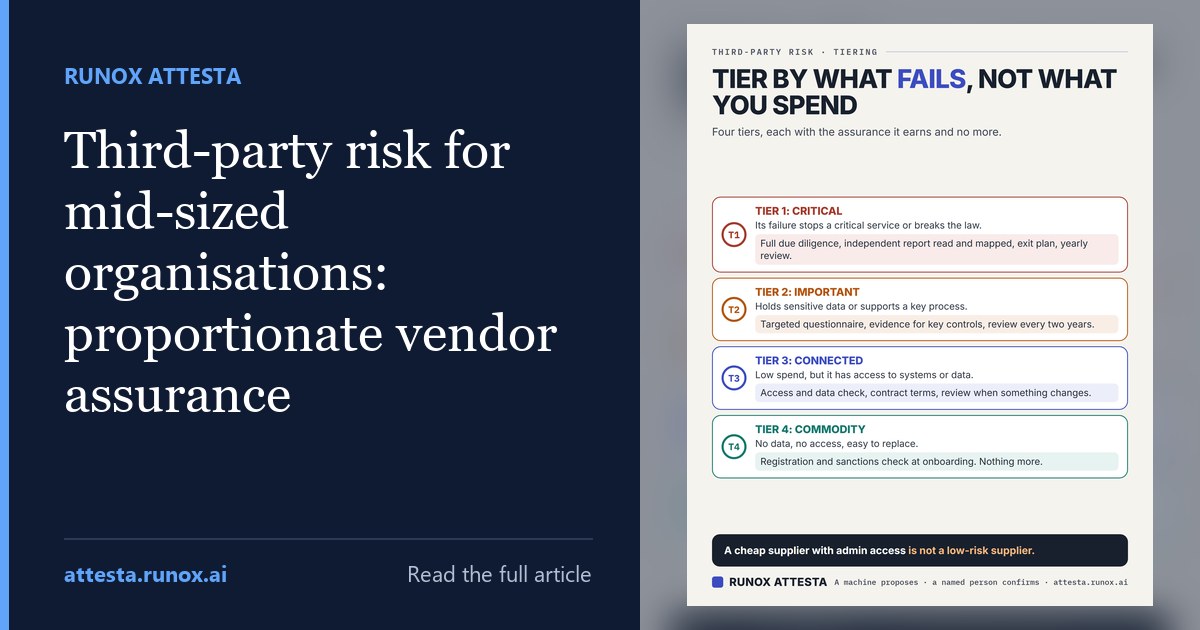
Audit & AssuranceTier suppliers by what fails, not by spend. Find the real supplier list first, then spend assurance hours where they matter. A worked budget for 412.
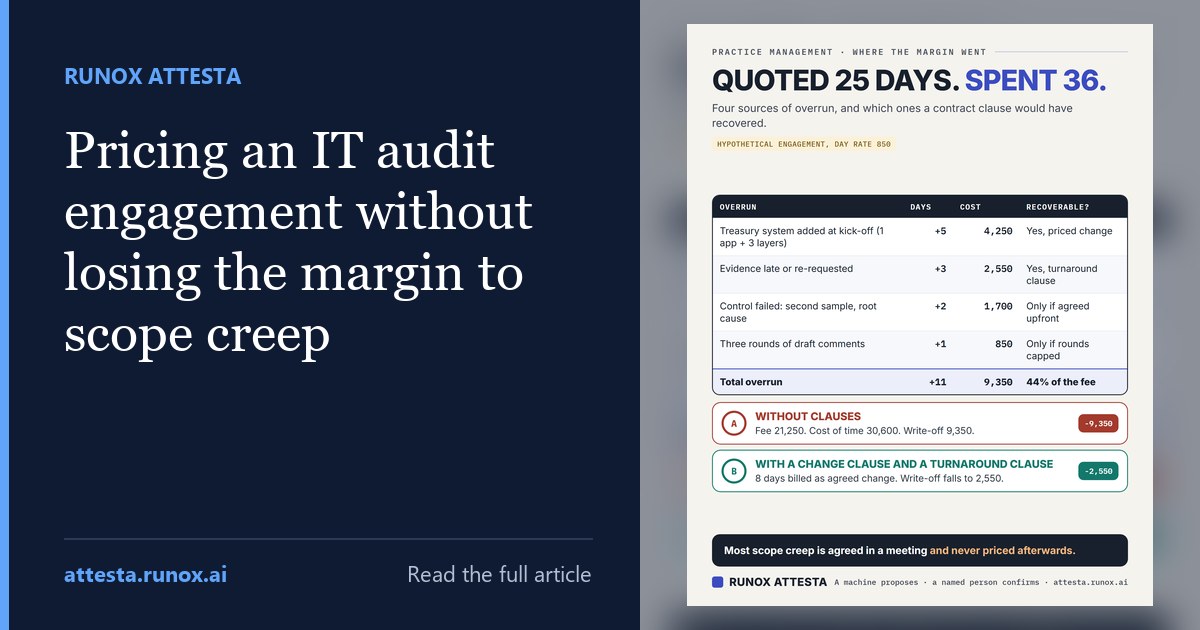
Audit & AssuranceQuoted 25 days, spent 36. Price IT audits in countable units, write six clauses before fieldwork, and price the change when it arrives.
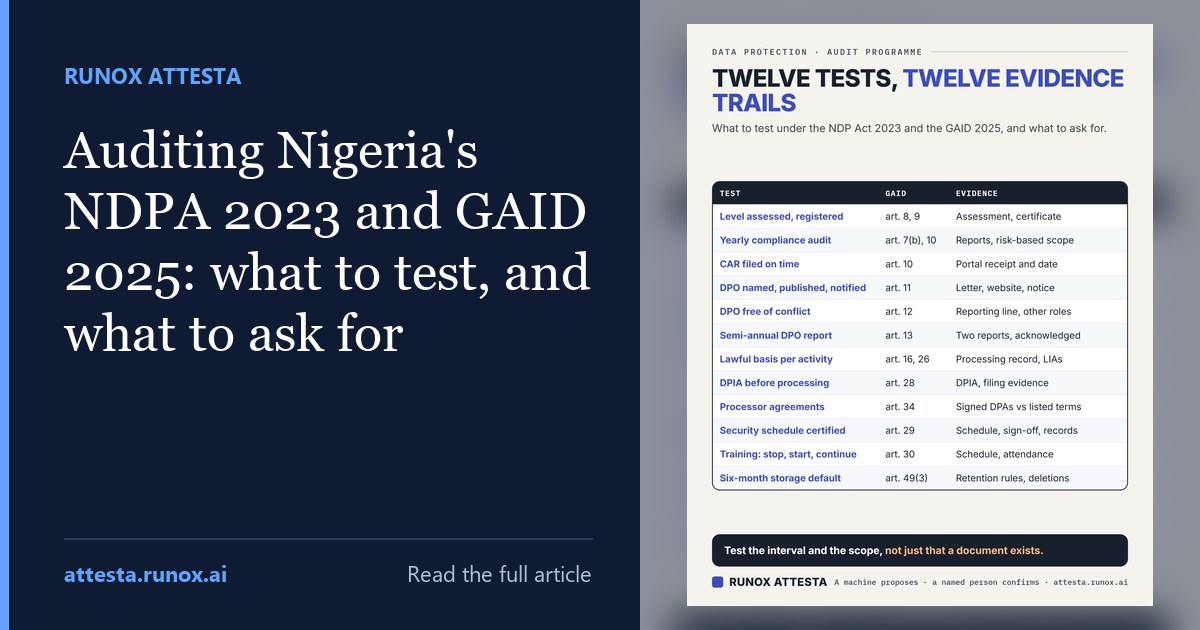
Audit & AssuranceA filed compliance return is prima facie good faith, not proof. Twelve tests for an NDPA and GAID 2025 audit, and the evidence each one needs.
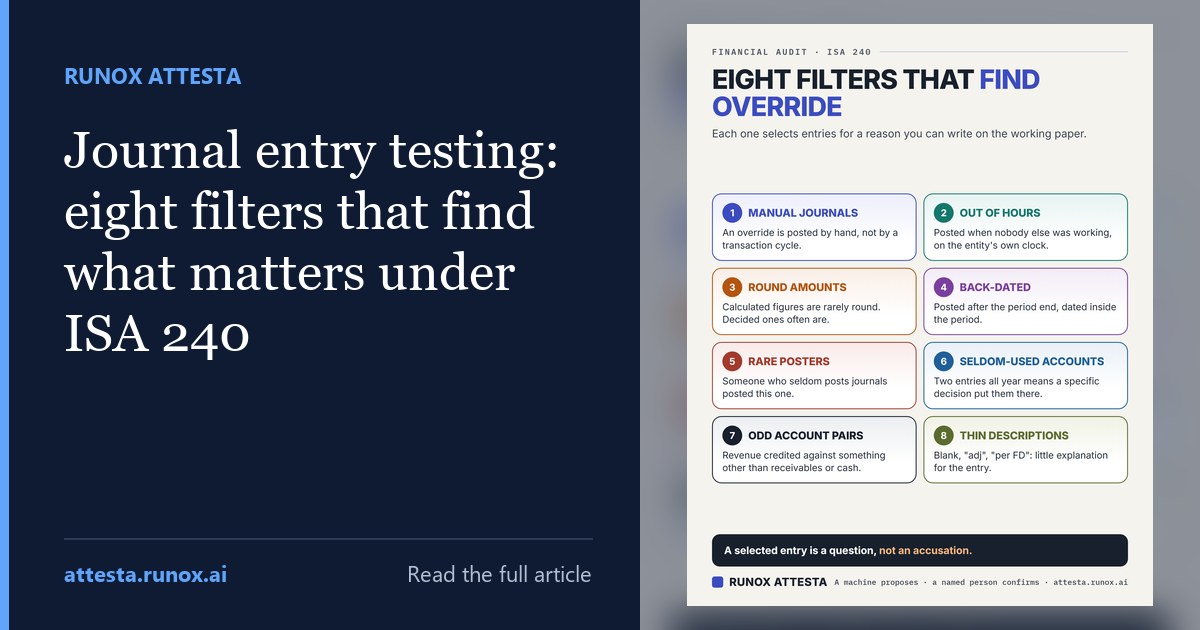
Audit & AssuranceRandom journals find nothing. Prove the population, then run eight filters with a reason you can write down. A worked year-end from 186,400 lines.
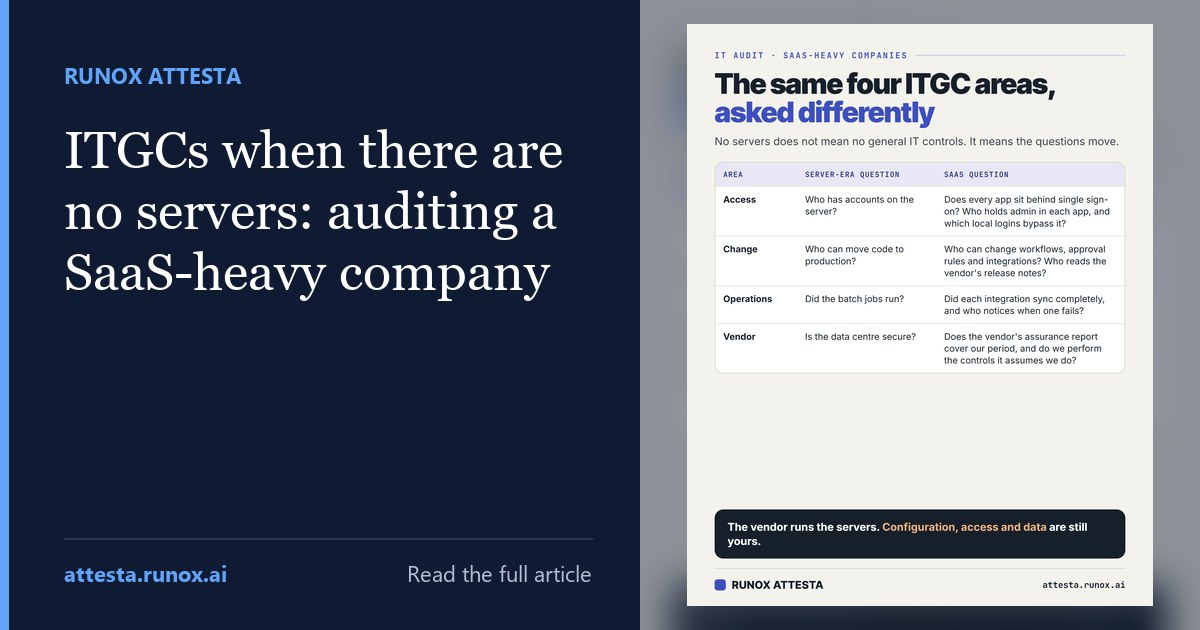
Audit & AssuranceNo servers does not mean no IT general controls. Access, change, operations and vendor risk move into identity, configuration and integrations.
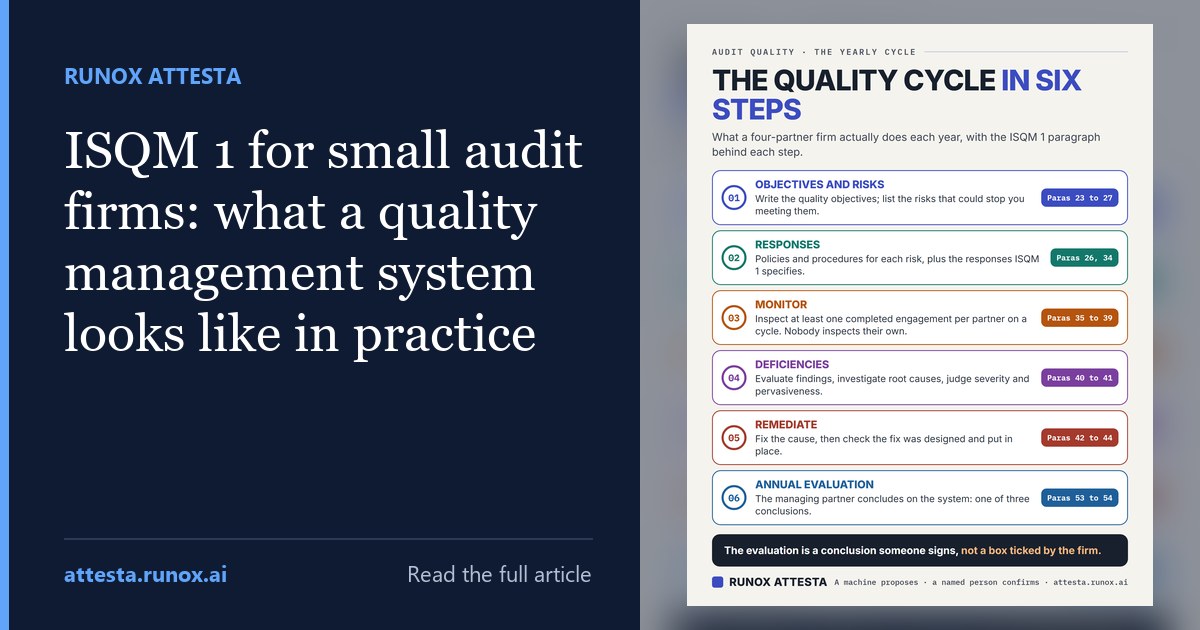
Audit & AssuranceISQM 1 scales down, but it does not go away. Eight components, a yearly cycle and the records an inspector will ask for, for a four-partner firm.
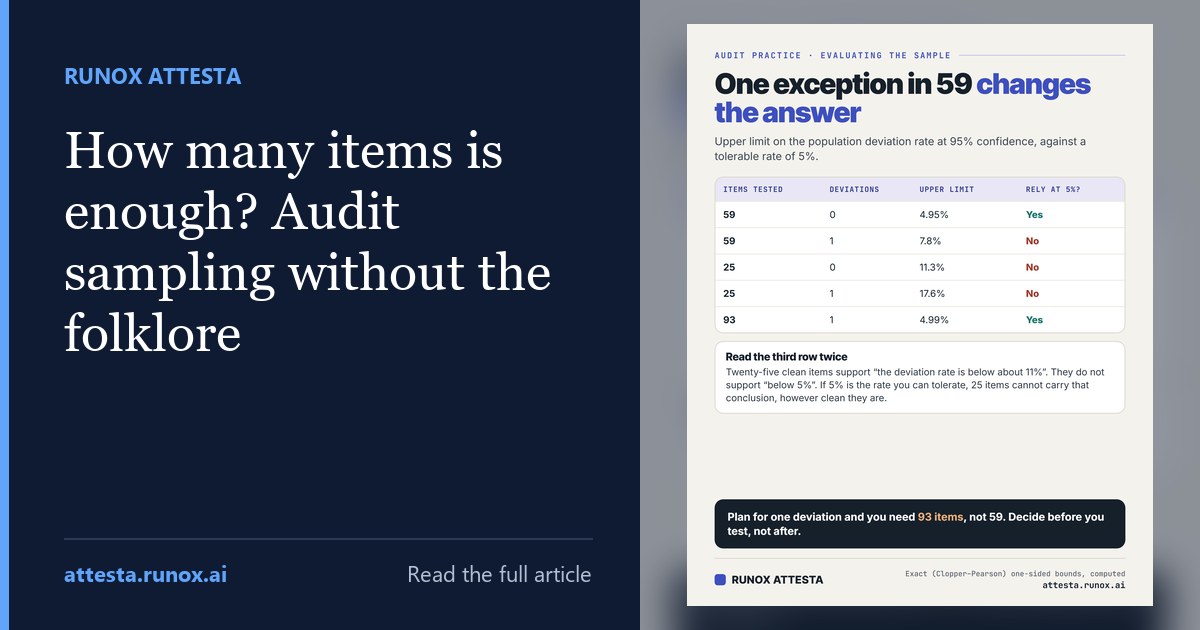
Audit & AssuranceISA 530 sets no sample size. 25 clean items cannot support a 5% conclusion. What the standard actually asks, with the arithmetic to check.
Join thousands of legal professionals receiving weekly insights on technology, compliance, and best practices.